
HAL, BEL, BDL, Zen, Astra Microwave: Q2 results preview, target prices; top defence pick
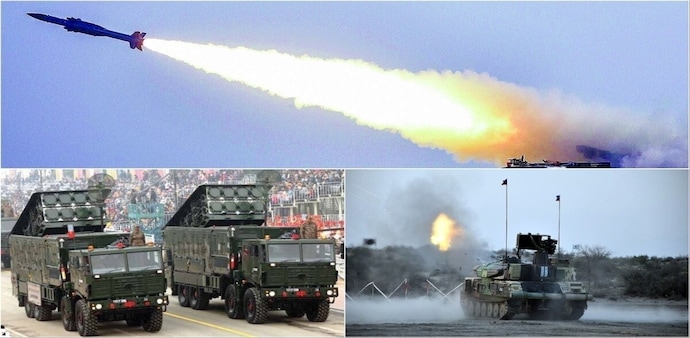
BDL Q2 results preview: High base of last year on lumpier execution may result in 19 per cent YoY decline in revenue, MOFSL said. Key monitorables included updates on inflows for Akash-NG and QRSAM.
- Oct 5, 2026,
- Updated Oct 5, 2026 9:24 AM IST
Ahead of the September quarter earnings season, MOFSL picked Bharat Electronics Ltd (BEL) as its top defence sector pick. In a results preview note, MOFSL said the defence sector has seen Defence Acquisition Council (DAC) approvals of Rs 1.62 lakh crore in FY27 so far and has a healthy pipeline ahead. It said total approvals of Rs 13 lakh crore over FY25-YTDFY27 have helped expand total addressable market (TAM) for domestic players, noting that the government is opening missile production to Indian private players, bolstered by approving DRDO to transfer technologies for all conventional missile systems to Indian industry for domestic production, implying higher private participation and larger TAM for non-PSU players.
MOFSL said the deadline for submitting Request for Proposal (RFP) for AMCA project has been shifted to October 30. "On aircraft space, HAL’s MD has committed to delivering 10 Tejas Mk-1A by Mar’27, supported by 10 F404-IN20 engines received till date, 12 more committed by GE Aerospace by Dec’26, and 27 completed airframes. We believe the key monitorables going ahead are: QRSAM (CCS clearance awaited), Akash-NG, P75I (CCS approval awaited), landing platform docks, next-gen corvettes and frigates, Mk1A deliveries, and AMCA announcements, especially on higher private participation," MOFSL said.
Here's what its Q2 expectations are from key defence companies:
Bharat Dynamics Ltd (BDL) target price MOFSL expects a sharp sequential improvement in BDL revenue on execution pick up for Akash and Astra Mk-1 project from Q2FY27 onwards. High base of last year on lumpier execution may result in 19 per cent YoY decline in revenue. "We will watch out for updates on BDL’s steps for supply chain management and commencement of the new facilities, bringing in Torpedo and mine orders. We expect margins to fall by 130 bps YoY to 15 per cent, because of higher bought out components for Akash and Astra Mk1 platforms," MOFSL said.
It said key monitorables included updates on inflows for Akash-NG and QRSAM. It revised its target on the BDL stock to Rs 1,210 as it factored in slightly lower margins in its estimates.
Bharat Electronics Ltd (BEL) target price
MOFSL expects BEL to report a revenue growth of 16 per cent YoY, led by the healthy execution of the opening order book of Rs 72,000 crore. Key monitorables included updates on large orders, including QRSAM, Uttam radars, next-gen corvettes, P75I submarines, etc., as well as status AMCA prototype.
"We expect margins to fall by 170 bps YoY to 27.7 per cent, due to execution of a changing product mix. The finalisation of orders, execution of the huge backlog, incremental share of exports, and further indigenization of modules and subsystems will remain key focus areas," MOFSL said.
The brokerage suggested a target of Rs 530, implying 38 per cent potential upside.
Hindustan Aeronautics Ltd (HAL) target price
MOFSL expects HAL Q2 revenue to grow 14 per cent YoY, driven by deliveries of previously awarded LCA Mk-1, Dhruv NG helicopters and HTT-40 basic trainers while delivery of Tejas Mk-1A is still awaited. The execution of huge backlog, incremental inflows, MRO growth, and margin levels will be the key focus areas, it said. In HAL's case, MOFSL said EBITDA margin may expand 100 bps YoY to 24.5 per cent, led by final platform deliveries. Key monitorables, it said, included the updates on deliveries of Tejas Mk1A and HTT-40, engine deliveries by GE, other orders beyond Tejas and working capital cycle. MOFSL suggested a target of Rs 5,800 on the stock, hinting at 26 per cent potential upside.
Astra Microwave Products Ltd target price
MOFSL expects Astra Microwave to log revenue growth of 14 per cent YoY in Q2FY27, aided by the order book of Rs 2,200 crore. The domestic brokerage said it would watch for updates on orders for QRSAM, Virupaksha radar, etc. and initiatives and inflows for space and weather segments.
"We expect Ebitda margin to remain healthy at 22 per cent (- 30 bps YoY), led by product mix execution. Key monitorables include ordering improvement across larger platforms, margin sustainability, execution timeline of UTTAM radar and export opportunities," MOFSL said while suggesting 'Buy' and a target of Rs 1,900 on the stock, hinting at 17 per cent potential upside.
Zen Technologies Ltd target price
MOFSL expects Zen Technologies Ltd 's execution to increase sharply by 99 per cent, mainly led by execution of the anti-drone orders received in FY26. It said key monitorables included conversion of pipeline into firm orders across both simulator and anti-drone, execution ramp-up of equipment orders and margin trajectory.
"We expect Ebitda margin to remain healthy at 32 per cent, which can improve going forward as high-margin simulator orders get executed. We will watch out for update on similar order execution, performance update of subsidiaries, traction in inflows from fast-track procurement, and export momentum," MOFSL said.
MOFSL suggested a target of Rs 1,600 on the stock.