
Historic! Home loans in India are now cheaper than the US -- What NRIs must know
Historic! Home loans in India are now cheaper than the US -- What NRIs must know
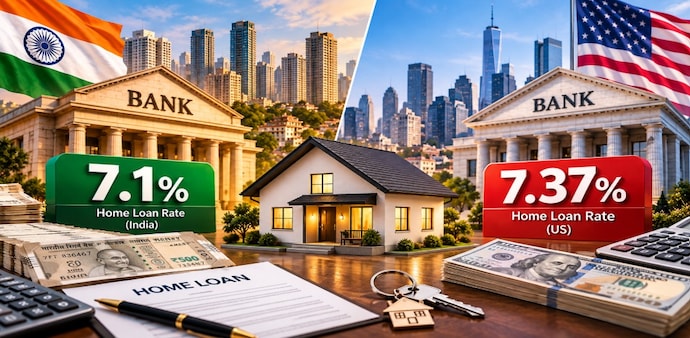
For generations, costly home loans were the norm for India’s middle class, while cheaper borrowing was associated with Western economies. That equation has now flipped, with US 30-year home-loan rates above 7.3% versus rates starting around 7.1% at several Indian lenders.
Business Today Desk
- Sep 26, 2026,
- Updated Sep 26, 2026 5:00 AM IST
For generations of middle-class Indians, expensive home loans were the norm, while cheaper borrowing was associated with Western economies. That equation has now flipped, with US 30-year fixed home-loan rates above 7.3% versus rates starting around 7.10% at several Indian public-sector lenders.
For NRIs and OCIs, however, the comparison goes beyond interest rates, with currency movements, rental yields, loan structures and transaction costs shaping the economics of property ownership.
Advertisement
Uma Shashikant, Chairperson, Centre for Investment Education and Learning, wrote about the financial implications for NRIs and OCIs in July 2026, arguing that buying property in India with dollar income can make less financial sense than it appears because of currency risk, lower rental yields and differences in financing and taxation. Her comments predate the latest US-India rate comparison as of September 25, 2026.
However, the latest data shows in September 2026 how sharply the equation has changed. The US 10-year Treasury yield is currently at 5.167%, a 20-year high, while the US 30-year fixed home-loan rate has climbed to 7.37%. Home-loan rates closely track the 10-year Treasury yield. Persistent inflation, tariff uncertainty and concerns over the US debt burden have kept Treasury yields elevated.
Advertisement
In India, baseline home-loan rates at several PSU banks currently start at around 7.10% for eligible borrowers, making the headline borrowing rate lower than in the US.
The shift is particularly striking compared with the post-Covid period. In 2020-21, US home-loan rates were around 2.65%, against 6.50% in India. By 2023-24, the rates had risen to around 7.80% in the US and 8.50% in India. The latest figures therefore represent a significant reversal in the relative borrowing-cost equation.
Why US home-loan rates have overtaken India
The drivers are different across the two economies. Higher US Treasury yields reflect, among other factors, concerns over the country's large debt burden, while sticky core inflation and tariff uncertainty have constrained the Federal Reserve's room to lower rates.
Advertisement
In India, economic resilience, relatively well-capitalised banks and the repo-rate-linked lending framework have supported the transmission of policy-rate changes to retail borrowers. The difference highlights how monetary policy, inflation and government borrowing can influence the cost of housing finance.
Why NRIs need to look beyond rates
Shashikant's July analysis highlighted the currency risk faced by NRIs and OCIs earning in dollars. A weakening rupee can reduce the dollar value of an Indian property and its capital appreciation, even when its value rises in rupee terms.
She also estimated Indian property rental yields at 3-5% gross and 1.5-2% after costs, compared with around 7% gross and 4-5% net in the US, depending on location.
Speaking about the current scenario, Rishi Singh, Founder & CEO, Silverdome Realtors, said the comparison should also consider how homes are financed. In the US, 30-year loans are widely available, allowing eligible buyers to spread repayments over 360 monthly instalments, while relatively lower down payments in some cases can reduce upfront capital requirements.
Advertisement
“In the US, 30-year mortgages are widely available, allowing eligible buyers to spread the cost of a property over 360 monthly payments,” Singh said. Depending on the lender and borrower profile, relatively lower down payments may also reduce the upfront capital requirement and make monthly housing costs more comparable with rent.
India's financing market has also evolved, with longer loan tenures and improved access to home loans making ownership more accessible. However, buyers in major cities still need to account for down payments and transaction-related costs.
Pawan Sharma, Managing Director, TRG Group, said US transactions can also be more straightforward because of standardised property deeds and processes such as escrow, while Indian buyers may need more extensive title searches and deal with varied ownership documents across jurisdictions.
"In the US, standardisation of property deeds, as well as the process of buying houses with financing systems and processes like escrow, can help make transactions more straightforward. In India, buyers are required to conduct more complex title searches and deal with various ownership documents, since state and local jurisdictions differ."
India, he added, has been moving towards greater transparency and regulation.
For NRIs and OCIs, therefore, the September 25 rate advantage in India is only one part of the calculation. Currency movements, rental yields, financing costs, loan tenure, upfront capital, taxation, transaction processes and liquidity remain important when deciding where dollar income should be deployed.
Advertisement
For generations of middle-class Indians, expensive home loans were the norm, while cheaper borrowing was associated with Western economies. That equation has now flipped, with US 30-year fixed home-loan rates above 7.3% versus rates starting around 7.10% at several Indian public-sector lenders.
For NRIs and OCIs, however, the comparison goes beyond interest rates, with currency movements, rental yields, loan structures and transaction costs shaping the economics of property ownership.
Advertisement
Uma Shashikant, Chairperson, Centre for Investment Education and Learning, wrote about the financial implications for NRIs and OCIs in July 2026, arguing that buying property in India with dollar income can make less financial sense than it appears because of currency risk, lower rental yields and differences in financing and taxation. Her comments predate the latest US-India rate comparison as of September 25, 2026.
However, the latest data shows in September 2026 how sharply the equation has changed. The US 10-year Treasury yield is currently at 5.167%, a 20-year high, while the US 30-year fixed home-loan rate has climbed to 7.37%. Home-loan rates closely track the 10-year Treasury yield. Persistent inflation, tariff uncertainty and concerns over the US debt burden have kept Treasury yields elevated.
Advertisement
In India, baseline home-loan rates at several PSU banks currently start at around 7.10% for eligible borrowers, making the headline borrowing rate lower than in the US.
The shift is particularly striking compared with the post-Covid period. In 2020-21, US home-loan rates were around 2.65%, against 6.50% in India. By 2023-24, the rates had risen to around 7.80% in the US and 8.50% in India. The latest figures therefore represent a significant reversal in the relative borrowing-cost equation.
Why US home-loan rates have overtaken India
The drivers are different across the two economies. Higher US Treasury yields reflect, among other factors, concerns over the country's large debt burden, while sticky core inflation and tariff uncertainty have constrained the Federal Reserve's room to lower rates.
Advertisement
In India, economic resilience, relatively well-capitalised banks and the repo-rate-linked lending framework have supported the transmission of policy-rate changes to retail borrowers. The difference highlights how monetary policy, inflation and government borrowing can influence the cost of housing finance.
Why NRIs need to look beyond rates
Shashikant's July analysis highlighted the currency risk faced by NRIs and OCIs earning in dollars. A weakening rupee can reduce the dollar value of an Indian property and its capital appreciation, even when its value rises in rupee terms.
She also estimated Indian property rental yields at 3-5% gross and 1.5-2% after costs, compared with around 7% gross and 4-5% net in the US, depending on location.
Speaking about the current scenario, Rishi Singh, Founder & CEO, Silverdome Realtors, said the comparison should also consider how homes are financed. In the US, 30-year loans are widely available, allowing eligible buyers to spread repayments over 360 monthly instalments, while relatively lower down payments in some cases can reduce upfront capital requirements.
Advertisement
“In the US, 30-year mortgages are widely available, allowing eligible buyers to spread the cost of a property over 360 monthly payments,” Singh said. Depending on the lender and borrower profile, relatively lower down payments may also reduce the upfront capital requirement and make monthly housing costs more comparable with rent.
India's financing market has also evolved, with longer loan tenures and improved access to home loans making ownership more accessible. However, buyers in major cities still need to account for down payments and transaction-related costs.
Pawan Sharma, Managing Director, TRG Group, said US transactions can also be more straightforward because of standardised property deeds and processes such as escrow, while Indian buyers may need more extensive title searches and deal with varied ownership documents across jurisdictions.
"In the US, standardisation of property deeds, as well as the process of buying houses with financing systems and processes like escrow, can help make transactions more straightforward. In India, buyers are required to conduct more complex title searches and deal with various ownership documents, since state and local jurisdictions differ."
India, he added, has been moving towards greater transparency and regulation.
For NRIs and OCIs, therefore, the September 25 rate advantage in India is only one part of the calculation. Currency movements, rental yields, financing costs, loan tenure, upfront capital, taxation, transaction processes and liquidity remain important when deciding where dollar income should be deployed.
Advertisement
Read more!