
Maruti Suzuki shares climb after Q2 results; brokerages flag demand risks, track new launches
Jefferies cut MSIL's FY27-29 earnings per share (EPS) estimates by 7-11 per cent and reduced its price target to Rs 13,500 from Rs 16,500 earlier, while retaining its 'Buy' rating.
- Oct 28, 2026,
- Updated Oct 28, 2026 5:11 PM IST
Shares of Maruti Suzuki India Ltd (MSIL) rose 0.83 per cent on Wednesday to settle at Rs 11,550 following the country's largest carmaker's second quarter (Q2 FY27) earnings announcement a day earlier. At the closing level, the stock remains down 30.90 per cent so far in calendar year 2026.
Jefferies cut MSIL's FY27-29 earnings per share (EPS) estimates by 7-11 per cent and reduced its price target to Rs 13,500 from Rs 16,500 earlier, while retaining a 'Buy' rating.
"Sep-Q EBITDA fell 6 per cent YoY, broadly inline with JEFe. EBITDA margin rose 70bp QoQ, but was still down 3ppt YoY. While industry registration growth has come off in recent weeks, MSIL was sanguine and expects 10 per cent domestic growth in 2H. Margin outlook remains clouded, although MSIL's market share is showing some stabilisation and its 20x FY28E PE is reasonable," the global brokerage said.
Nomura kept its 'Neutral' tag and lowered MSIL's target price to Rs 13,046 from Rs 14,071 earlier, citing demand-related risks, particularly for hatchbacks in FY28.
"We do remain watchful of demand risks in FY28F particularly for hatchbacks considering the risks from higher interest rates, inflation, weak monsoons and oil prices. Small cars and vans (non SUVs) which form ~58 per cent of MSIL volumes are more vulnerable to these risks," Nomura said.
It, however, stated, "We believe drivers for EV inflection are in place and stronger EV growth may impact MSIL's market share. We maintain our Neutral rating."
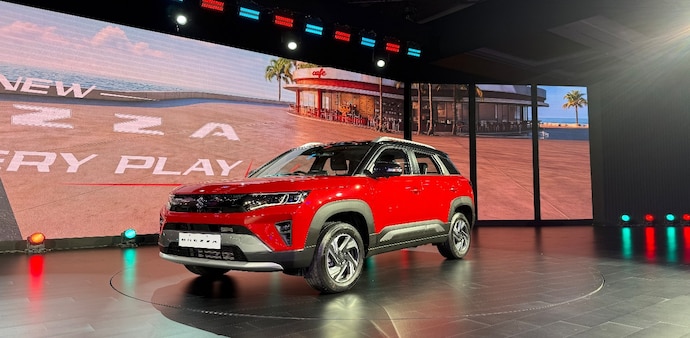
The brokerage also highlighted promising bookings for the new Brezza. "Brezza bookings remained encouraging, with 35 per cent of bookings for the 1.0L turbo petrol variant and another 35 per cent for the underbody CNG variant," it said.
Meanwhile, MOFSL noted that MSIL's Q2 FY27 profit after tax (PAT) came in below its estimate due to mark-to-market (MTM) losses, which resulted in lower other income. The domestic brokerage expects the company to deliver an 11 per cent earnings compound annual growth rate (CAGR) over FY26-28.
"We expect MSIL to deliver an 11 per cent earnings CAGR over FY26–28E. Reiterate BUY with a TP of Rs 14,800, valuing the stock at 26x FY28E EPS," MOFSL said.
JM Financial also retained its 'Buy' rating while trimming its target price to Rs 14,170 from Rs 14,610 earlier.
"We maintain our BUY rating with a revised TP of Rs 14,170 (Rs 14,610 earlier), valuing the stock at 25x Sep'28E EPS," JM stated.
Choice Institutional Equities upgraded its rating on MSIL to 'BUY' from 'ADD' and set a target price of Rs 13,500. The brokerage cited the recent share price correction, domestic market-share gains, refreshed models, capacity expansion and improving demand for small cars.
Choice said, "The refreshed Baleno introduced Level 2 ADAS and other premium features. MSIL contributed over 51 per cent of India's PV exports in H1 FY27, despite logistics disruption. Fronx crossed 2,00,000 cumulative exports in under 38 months."
It also cited encouraging bookings for the new Brezza as a factor supporting its assessment of the company's growth outlook.
Shares of Maruti Suzuki India Ltd (MSIL) rose 0.83 per cent on Wednesday to settle at Rs 11,550 following the country's largest carmaker's second quarter (Q2 FY27) earnings announcement a day earlier. At the closing level, the stock remains down 30.90 per cent so far in calendar year 2026.
Jefferies cut MSIL's FY27-29 earnings per share (EPS) estimates by 7-11 per cent and reduced its price target to Rs 13,500 from Rs 16,500 earlier, while retaining a 'Buy' rating.
"Sep-Q EBITDA fell 6 per cent YoY, broadly inline with JEFe. EBITDA margin rose 70bp QoQ, but was still down 3ppt YoY. While industry registration growth has come off in recent weeks, MSIL was sanguine and expects 10 per cent domestic growth in 2H. Margin outlook remains clouded, although MSIL's market share is showing some stabilisation and its 20x FY28E PE is reasonable," the global brokerage said.
Nomura kept its 'Neutral' tag and lowered MSIL's target price to Rs 13,046 from Rs 14,071 earlier, citing demand-related risks, particularly for hatchbacks in FY28.
"We do remain watchful of demand risks in FY28F particularly for hatchbacks considering the risks from higher interest rates, inflation, weak monsoons and oil prices. Small cars and vans (non SUVs) which form ~58 per cent of MSIL volumes are more vulnerable to these risks," Nomura said.
It, however, stated, "We believe drivers for EV inflection are in place and stronger EV growth may impact MSIL's market share. We maintain our Neutral rating."
The brokerage also highlighted promising bookings for the new Brezza. "Brezza bookings remained encouraging, with 35 per cent of bookings for the 1.0L turbo petrol variant and another 35 per cent for the underbody CNG variant," it said.
Meanwhile, MOFSL noted that MSIL's Q2 FY27 profit after tax (PAT) came in below its estimate due to mark-to-market (MTM) losses, which resulted in lower other income. The domestic brokerage expects the company to deliver an 11 per cent earnings compound annual growth rate (CAGR) over FY26-28.
"We expect MSIL to deliver an 11 per cent earnings CAGR over FY26–28E. Reiterate BUY with a TP of Rs 14,800, valuing the stock at 26x FY28E EPS," MOFSL said.
JM Financial also retained its 'Buy' rating while trimming its target price to Rs 14,170 from Rs 14,610 earlier.
"We maintain our BUY rating with a revised TP of Rs 14,170 (Rs 14,610 earlier), valuing the stock at 25x Sep'28E EPS," JM stated.
Choice Institutional Equities upgraded its rating on MSIL to 'BUY' from 'ADD' and set a target price of Rs 13,500. The brokerage cited the recent share price correction, domestic market-share gains, refreshed models, capacity expansion and improving demand for small cars.
Choice said, "The refreshed Baleno introduced Level 2 ADAS and other premium features. MSIL contributed over 51 per cent of India's PV exports in H1 FY27, despite logistics disruption. Fronx crossed 2,00,000 cumulative exports in under 38 months."
It also cited encouraging bookings for the new Brezza as a factor supporting its assessment of the company's growth outlook.