















 UBS remains positive about the sector's prospects and anticipates strong Q2 Ebitda growth.
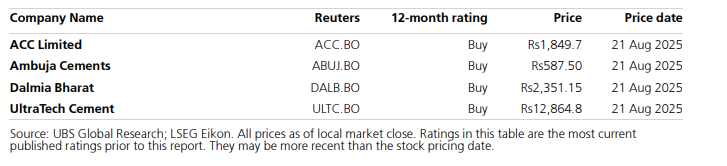
UBS identified Ambuja Cements, UltraTech Cement, and Dalmia Bharat Ltd as its top investment picks from the cement sector. The brokerage highlighted its continued optimism for the sector despite a less-than-expected demand growth in the first quarter of FY26.
Cement volumes grew by 3% year-on-year in Q1, falling short of the anticipated 10% growth. The demand shortfall was attributed to an early monsoon, which impacted consumer discretionary segments. Nonetheless, companies in the sector have maintained a positive outlook, with Ambuja Cements even raising its volume guidance for FY26 by 100 basis points, reflecting confidence in future demand.

 HDFC Bank shares: Carlisle investors to approach PMO over alleged mis-selling, says report
 $119 mn in Iranian oil trade: US sanctions four Indian firms, three nationals under Trump's economic offensive
 Iran, Oman discuss temporary corridor through Hormuz, to clear it of mines
 Block deals today: Welspun Corp, Groww to see Rs 3,322 crore worth shares changing hands
 ‘Incredibly troubling to see…’: NYC Mayor Zohran Mamdani says he opposes RSS chief Mohan Bhagwat’s event at Madison Square
 Trump Moves To Make H-1B Visa Fee Permanent And Higher: What It Means For Indians
 Market Rally Vs Geopolitical Risk: What Wins From Here? Aditya Agarwal
 Daily Calls: Ask Your STOCK MARKET TODAY QUERIES | Market Update | Share Market News Today
 Symbiotec Pharmalab IPO | Top Management On Growth Plans, Business Outlook & IPO Strategy
 Chennai Second Airport Halted: Parandur Project Faces Wetland Concerns & Political Storm

 PhysicsWallah block deal: Equity worth Rs 550 crore changes hands; stock climbs
 Gaja Alternative Asset Management shares make a decent market debut; stock lists at 16% premium
 HDFC Bank shares may fall to Rs 675-680, ICICI Bank a better pick, says Gaurav Sharma
 Augmont Enterprises IPO: Odds of share allotment, Ways to check application status, GMP & more
 Adani Energy shares gain after Rs 4,700 crore Maharashtra transmission project
 Caviar announces four luxury iPhone Ultra models ahead of Apple launch
 ‘No third party involved; we didn’t leak ceasefire details to US’: Ex-CDS Anil Chauhan on Op SindoorPhysicsWallah block deal: Equity worth Rs 550 crore changes hands; stock climbsGaja Alternative Asset Management shares make a decent market debut; stock lists at 16% premium HDFC Bank shares may fall to Rs 675-680, ICICI Bank a better pick, says Gaurav Sharma


