

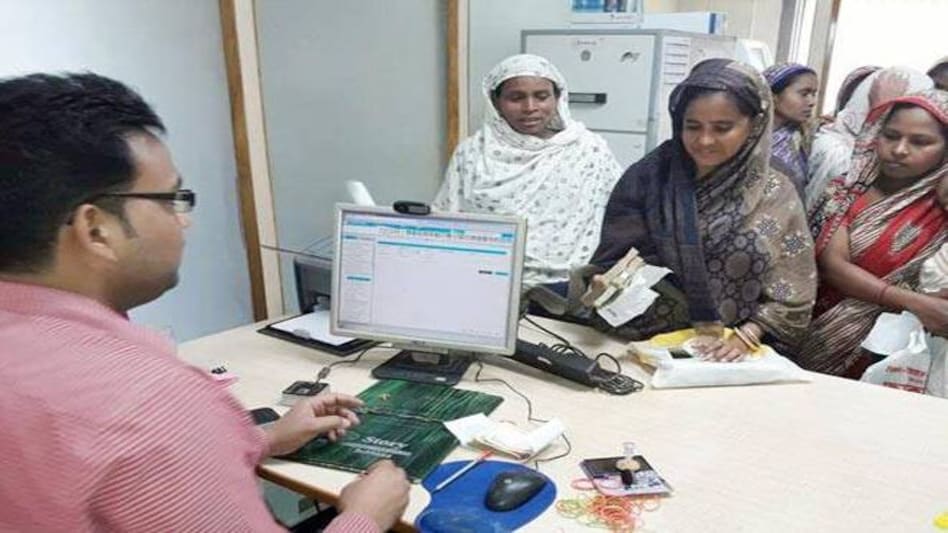
In emerging markets and rural areas, traditional banks have a hard time reaching customers. Opening and operating traditional bank branches are often not cost-effective. Operating a bank branch entails having at least one teller at the front desk, a bank manager and bank employees specialising in areas such as mortgages and loans, and security. It is one of the reasons why banks are closing rural branches. Rural customers also have to travel extensively to visit their respective bank branches. For instance, an average rural customer of the State Bank of India has to travel around 8-20 km to the closest branch, according to statistics by Reserve Bank of India.
In such a scenario, agent banking, comprising a network of banking agents who act as physical bank branches, is the answer. Banking agents can be telcos, e-wallet providers, retailers and so on. It is extremely convenient as the travel distance to, say a telco agent, is less than 2 km for that same SBI bank customer.
 Hormuz crisis exposed world's energy weak spots: Why the next shock could hurt more
 'AI ending humanity is nonsense': Ex-Infosys CEO Vishal Sikka rejects growing doom warnings
 Food delivery, quick commerce largely shielded from UPI MDR despite high digital payments
 Could AI really kill us all? Here’s what MIT researchers fear and what they don’t
 New e-commerce rules: How online discounts and search rankings will change
 Gold Price Target 2026: Expert Sees MCX Gold At ₹1.8 Lakh By Year-End Amid Strong Demand
 Health Insurance: Why Pre-Existing Diseases And Waiting Periods Matter For Buyers
 Crude Oil Above $100: How High Energy Prices And Rupee Weakness Impact Gold Prices In India
 CEA On India’s Manufacturing Rise, Atmanirbhar Bharat And Modi’s Economic Policy
 Health Insurance Buying Guide: 7 Things First-Time Buyers Must Check Before Choosing A Policy

 SpaceX weight in Nasdaq 100 to jump to 2.82% following quarterly index rebalance: Report
 Tata Motors or Ashok Leyland? Analyst reveals his preferred auto stock for near-term gains
 Maharashtra Scooters, Dixon Tech, Bharat Dynamics, Jai Corp among stocks to turn ex-dividend on Monday
 Jindal Supreme, SS Retail, Hero Motors IPOs subscribed up to 181 times on final day; details here
 Sensex, Nifty post sixth weekly loss; TCS, Titan among top laggards, slip up to 4%
 iPhone 18 Pro launches ahead of Navratri, Diwali, but grocery and BPC could steal festive e-commerce spotlight: Report
 ‘Very big things are coming’: Trump in ‘deciding mode’ as Iran sets 7 key demands
 EV charging demand is moving beyond metros: Vijayawada, Rajamahendravaram among fastest-growing marketsFood delivery, quick commerce largely shielded from UPI MDR despite high digital paymentsNew e-commerce rules: How online discounts and search rankings will change













