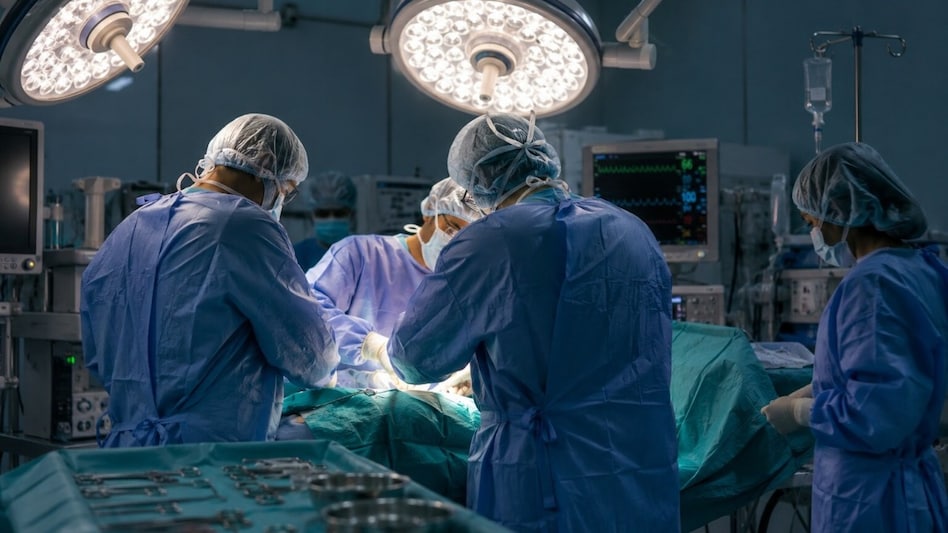
 The findings reflect the expansion underway across the hospital sector, with companies adding beds through greenfield and brownfield projects, partnerships and acquisitions.
India's healthcare sector posted growth in FY26, led by hospitals and diagnostic chains, as higher patient volumes, capacity additions and continued investor interest supported the industry, according to an EY-Parthenon report.
The report said major hospital operators recorded revenue and EBITDA growth of more than 15% year-on-year during FY26. Occupancy levels remained between 60% and 75%, while higher average revenue per occupied bed (ARPOB) and greater contribution from specialties such as cardiology and oncology supported earnings.

 UPI stays free: Finance Ministry bars charges on transactions up to Rs 2,000
 'Don't kill the Golden Goose': Trump says US must keep its AI lead over China
 Made-in-India cars are winning over Japan! Maruti powers nearly two-thirds of Suzuki's global production
 Amazon bets big on value commerce as Bazaar grows 5X, expands beyond Tier-2 and Tier-3 India
 Inflation heats up: Food prices rise, crude crosses $100; what it means for your wallet
 Why Crude Oil Prices Are Rising Again Now?
 Modi Xi Meet After 7 Years In India Signals Possible Reset In Bilateral Ties
 BRICS Summit 2026: India Secures New Delhi Declaration After Intense Negotiations
 BRICS Summit 2026: Modi’s Big Diplomatic Win As New Delhi Declaration Gets Backing
 Dario Amodei, Sam Altman, Elon Musk Back AI Slowdown Call Amid Growing Safety Concerns

 Varun Beverages shares slip 25% from 52-week high; more downside ahead?
 Uno Minda gets 'IND A1+' credit rating for commercial papers from India Ratings
 Karnataka Bank, Pondy Oxides, ITDC, Blue Dart among stocks to turn ex-dividend on September 15
 Stock market outlook: Crude oil prices, US Fed's policy decision among key factors to watch out for this week
 Raghav Productivity Enhancers' subsidiary bags patents for quartz processing
 Want to run a shop at a railway station? Here’s how you can actually get one
 EV owners beware: These service mistakes could leave you with a costly repair bill
 A man used OpenAI's GPT-6 Astra to book IRCTC train ticket from Mumbai to Rajkot
 ₹1.25 lakh shock: This 3-wheel electric scooter could change city riding
 Ladakh’s Tso Kar rescue: Can 320 million litres of glacier water change its fate