 Housing construction one of the sectors to drive capital formation, says Axis Capital report
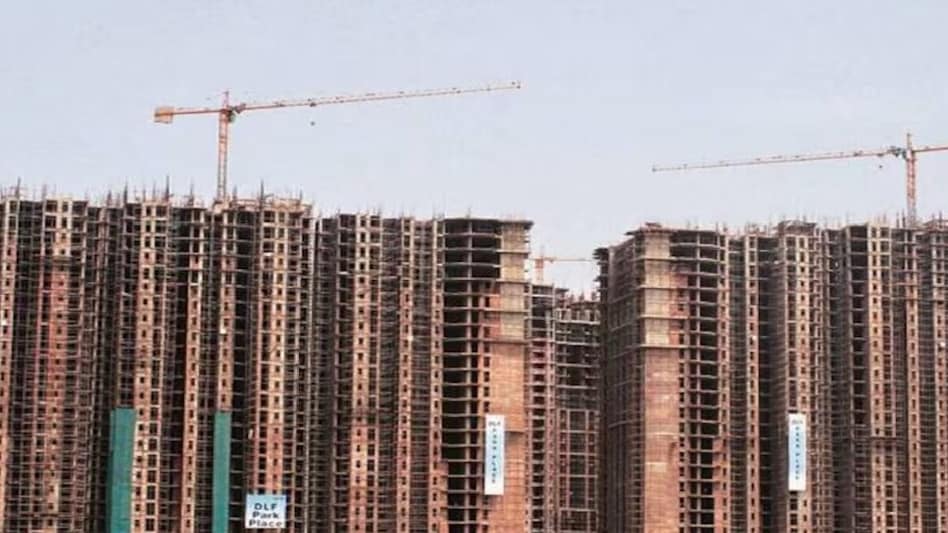
Housing, a sector struggling for the past few years, could be the foundation supporting a revival in India’s capex cycle. A report by Axis Capital has identified housing construction, power generation and a several other new sectors to power the country’s capital formation in the next six years.
“Going forward, we expect growth to be investment-led, with the investment ratio rebounding to 34 per cent by FY30,” the report anchored by Neelkanth Mishra, Head of Global Research, Axis Capital and Part-Time Member, Economic Advisory Council to the Prime Minister.

 AI race beyond US, China: Japan, South Korea emerge as leading AI-ready economies. How India fares
 Markets Next Week: Crude oil at $117, broader market selloff and Q2 earnings in focus
 'Using Starlink to kill people has never been allowed': Musk clears air on Ukraine demand
 Nifty correction: My portfolio is bleeding. Should I continue SIPs, invest a lump sum or wait for a fall?
 India-Mauritius tax treaty: What the new PPT means for grandfathered investments and capital gains
 What Are ETFs And BeES? How They Work, Key Differences And Benefits For Stock Market Investors
 Trump Says Europe Is In ‘Big Trouble’, Blames Immigration For France’s Unrest And Violence
 Renting Vs Buying A House: Gauri Chaddha Explains Tax Benefits And The Smarter Financial Choice
 Home Loans For Tax Savings? Why Buying A House Needs More Than Tax Benefits
 How To Choose The Right ETF: Sector Outlook, Risk, Benchmark Selection And Long-Term Investing Tips
 Markets Next Week: Crude oil at $117, broader market selloff and Q2 earnings in focus
 Jio Platforms IPO GMP at 21%: What could investors earn on listing day?
 Jio Platforms IPO: Record Rs 4.90 lakh crore in bids, 1.35 cr applications; check allotment odds
 IndusInd Bank Q2 profit at Rs 1,242 crore; NII up 4% YoY
 2. JSW Steel, Jindal Steel Q2 results: Revenue, profit rise; margins tell different stories
 Why smaller firms face higher failures: BCG study of 30,000 US firms reveals key risks
 Sanju Samson’s ultimate Rajini fan moment: Cricketer books whole theatre for Jailer 2
 FIFA opens bidding for 2030 World Cup US rights: Netflix, Disney, Amazon joins race'Using Starlink to kill people has never been allowed': Musk clears air on Ukraine demand
 Next major wave in retail broking will originate from smaller towns and villages: SEBI chief