


 BEL Q1 results: Antique Stock Broking estimated BEL's Q1 net profit at Rs 1,053.90 crore, up 8.8 per cent YoY. Sales are seen rising 16.4 per cent YoY to Rs 5,139.20 crore.
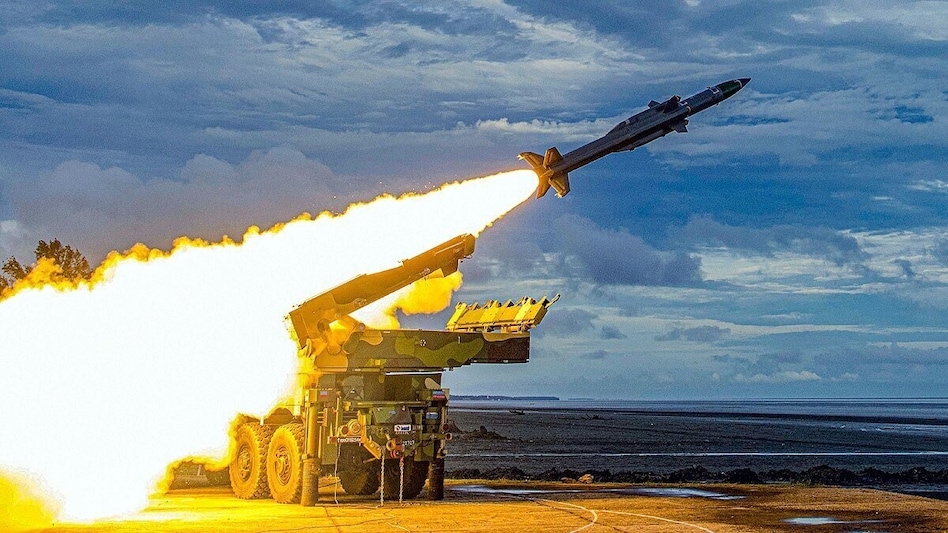
Defence PSU Bharat Electronics Ltd (BEL) is expected to report a net profit of Rs 1,086 crore for the June quarter on a net sales of Rs 5,108 crore during the same period. Ebitda for the Navratna firm is pegged at Rs 1,421 crore, Bloomberg consensus estimates showed. All eyes would be on updates on large orders, including QRSAM, Uttam radars, next-gen corvettes, P75I submarines, etc, as well as status AMCA, analysts said.
Ahead of its quarterly results, analysts are mostly positive on BEL, with the defence manufacturer having 28 'Buy' calls, one 'Hold' recommendation and three 'Sell' ratings. The consensus target price on the stock stands at Rs 490, which implies a 21 per cent potential upside ahead.

 'RBI letter does not mention listing': Noel Tata seeks full briefing on Tata Sons-RBI talks
 Tata Trusts asks Tata Sons to explore options other than listing, says ‘Tata Model has to be saved’
 Tata Trusts proposes ₹25,000 crore plan for SP Group, says Tata Sons listing is not an option
 Chandrasekaran had assured all necessary steps were being taken to remain private: Noel Tata
 'We cannot put the cart before...': Noel Tata's argument against N Chandrasekaran's reappointment
 How India Changed In 12 Years: PM Modi’s Journey From Economic Reforms To Viksit Bharat
 Modi @76: From Twitter To Instagram, How His Digital Outreach Has Evolved
 Stock Picks To Watch: Shibani Kurian Reveals Kotak AMC’s Market Bets
 Gold ETF vs Physical Gold: Know the Tax Rules, Charges and Key Differences
 PPF vs NPS: Tax Benefits, Returns and Lock-in Period Explained for Retirement Planning

 Hero Motors IPO subscribed 3.37 times on Day 2; retail portion subscribed over 5 times
 NSE IPO: India's largest exchange gets 43% subscription on Day 1; NIIs, retail see strong demand
 Rentomojo shares settle maiden trade nearly 32% above IPO price; what should investors do now?
 Sensex slips, Nifty settles higher; Tata stocks gain after N Chandrasekaran reappointment
 Cochin Shipyard, KRBL, RITES, Ramky Infrastructure among stocks to turn ex-dividend on September 18
 Maharashtra FDA action: Nair Hospital canteen, Olympia Coffee House licences suspendedChandrasekaran had assured all necessary steps were being taken to remain private: Noel Tata
 TVS Motor to increase monthly EV capacity to over 50,000 units as sales boom
 'Foreign investors want only returns': Noel Tata explains why he opposes listing Tata SonsTata Trusts proposes ₹25,000 crore plan for SP Group, says Tata Sons listing is not an option













