


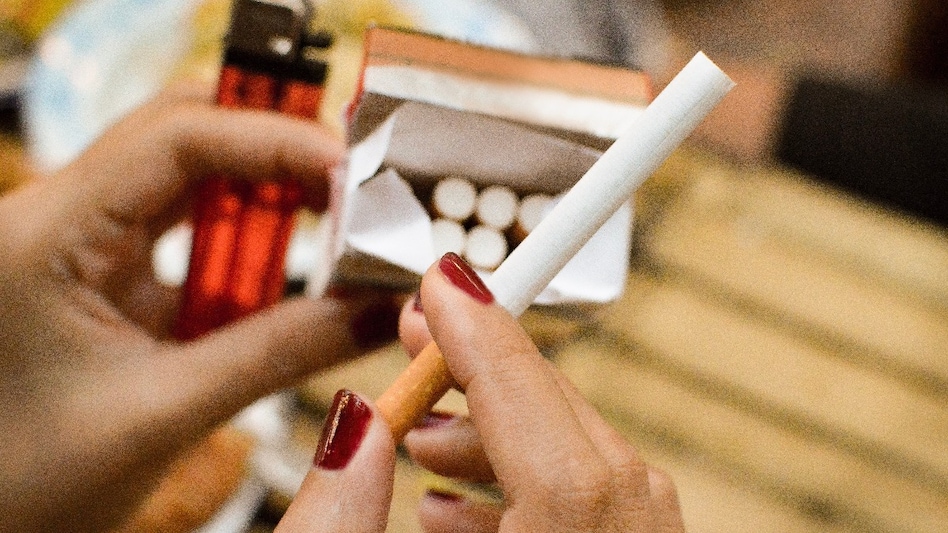
 The insurer failed to provide any medical evidence linking the policyholder’s lung cancer directly to his smoking habit.
Can your health insurance claim go up in smoke just because you’re a smoker? Not unless the insurer can prove that your illness was caused because of it—says a consumer court in a quirky but consequential ruling that just might give smokers some breathing room (though not medical advice).
Health insurance companies frequently deny claims associated with smoking or drinking-related conditions, such as liver diseases and lung cancers, citing them as intentional risks. They are concerned about the possibility of numerous claims if the individual persists in these unhealthy habits while managing pre-existing conditions caused by them. This can be perceived as endorsing the individual's self-destructive behavior. Consequently, insurers are discouraged from approving proposals involving such circumstances.

 Over 1 lakh EPFO subscribers set for automatic PF refunds as Centre verifies dormant accounts: Report
 Why Tata Sons got ₹28,291 cr from TCS in FY26, down from ₹32,184 cr in FY25
 ‘Extremely disturbing occurrence ’: MeitY reacts to removal of PM Modi video, seeks explanation from Meta
 Missed your minimum balance? Banks pocketed ₹26,100 cr in penalties in just 4 years
 L&T Q1 results: PAT rises 14% to Rs 4,123 crore; revenue up 7%
 Anti-Paper Leak Bill Debate: Jitendra Singh Lists Past Exam Leaks, Corners Opposition
 Tata Power Bets Big On 5.3 GW Pipeline! Management Sees Higher Margins & Strong FY27 Demand
 Term Insurance Vs Life Insurance: What's The Difference? | Personal Finance | Money Today
 Canara Bank Q1 Results Decoded | MD & CEO Brajesh Kumar Singh On Growth, NPAs & FY27 Outlook
 Daily Calls: Ask Your STOCK MARKET TODAY QUERIES | Market Update | Share Market News Today

 Moschip Technologies, Tamilnad Mercantile Bank shares: Here's what charts indicate
 Sensex, Nifty end lower as FMCG, energy weigh; IT stocks outperformL&T Q1 results: PAT rises 14% to Rs 4,123 crore; revenue up 7%
 Tata Capital Q1 results: PAT jumps 56% YoY to Rs 1,547 crore; AUM rises 22%
 KPIT Tech, Firstsource: What to do with these two battered IT stocks?
 Skyroot Aerospace sends world's first lab-grown diamond jewel into space aboard Vikram-1Moschip Technologies, Tamilnad Mercantile Bank shares: Here's what charts indicate
 'Were they terrorists?': Priyanka Gandhi asks why tear gas, lathis were used on protesting students
 HUL to further raise prices. Here’s how much
 '150 crore wrists to target': Gaurav Mehta eyes 100 Jaipur Watch Company stores in three years











