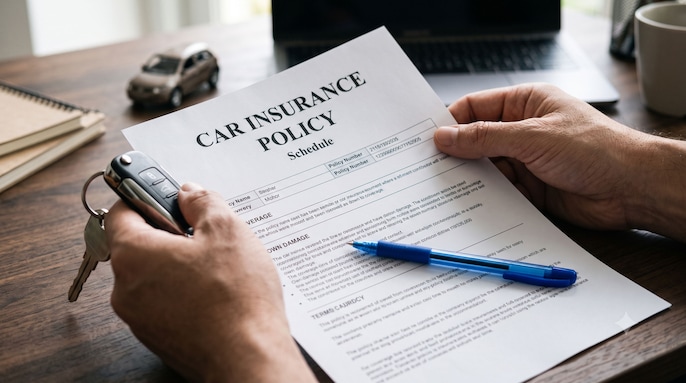
First, check whether your policy includes own-damage cover. A third-party-only policy does not cover damage to your own car. Comprehensive insurance includes wider protection, but the cause of damage and the policy’s exclusions still matter.
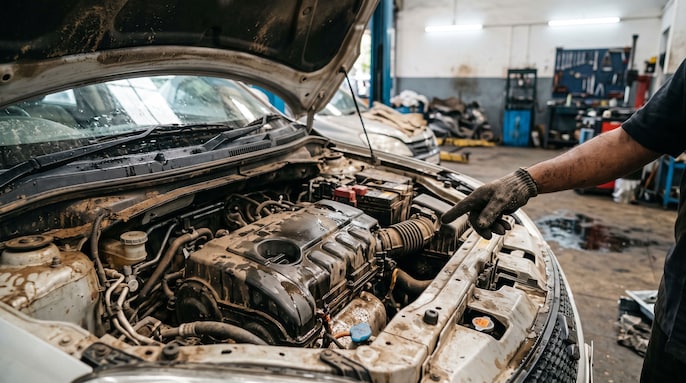
An own-damage policy can cover insured flood damage while excluding certain consequential engine losses. Look specifically for an engine-and-gearbox protection endorsement. HDFC ERGO’s published wording, for example, extends cover to specified internal damage from water ingress, subject to conditions.
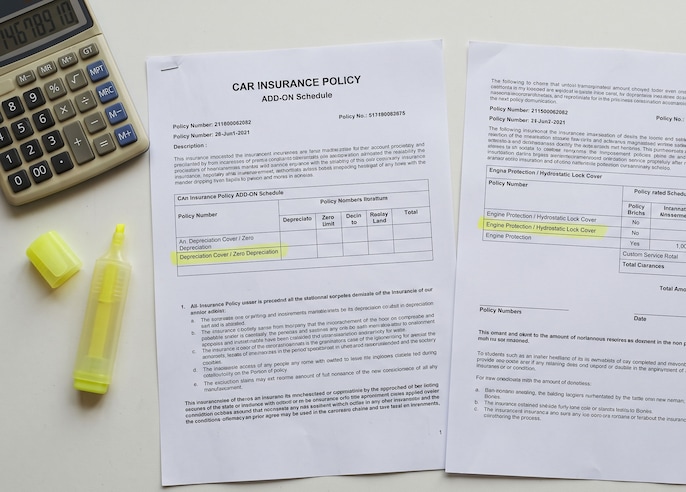
Zero-depreciation cover addresses depreciation deductions on eligible repairs. It does not automatically add protection for every cause of engine damage. Read the names and wording of the add-ons actually listed in your policy schedule.
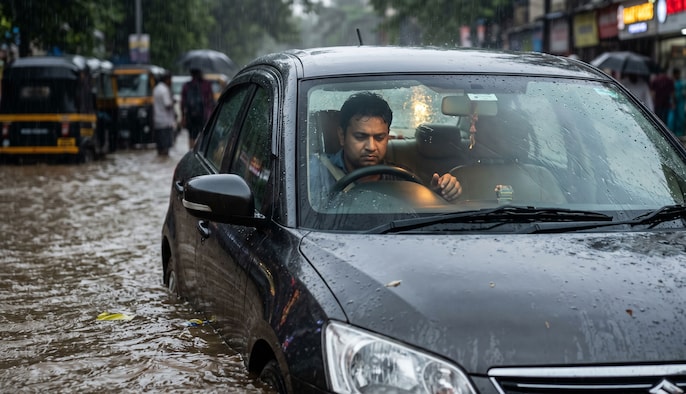
If the vehicle has stopped in water, resist cranking or push-starting the engine. HDFC ERGO’s engine-protection wording expressly requires this precaution. Move yourself to safety and contact your insurer or authorised assistance provider for instructions.
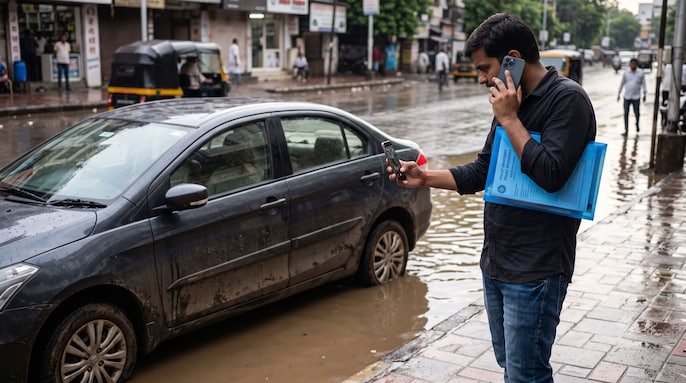
Register the claim promptly. Keep the policy number, location and incident details ready, and photograph the damage only where safe. Ask the insurer about inspection, recovery and garage approval before authorising dismantling or repairs. Claim procedures vary between policies.
Check deductibles, exclusions, reporting obligations and the assistance arrangements in your own contract. Some engine-protection wording excludes damage linked to delayed notification or retrieval. The useful question is: “What must I do for this particular cover to respond?”
 India's Next Connectivity Leap? Tata Communications Bets On Satcom & Smart Villages
 Motorola's Shivam Ranjan Speaks To Business Today About Motorola's Upcoming Flagship @ IMC26
 Is The AI Boom Sustainable? The Debate Over Investment Returns, India's AI Future And Job Disruption
 India-UK Trade Ties Set for Fresh Push? Goyal Calls for Faster Business Cooperation
 Rahul Gandhi Vs Gyanesh Kumar: 200 Officers Claim Escalates Election Commission Row