












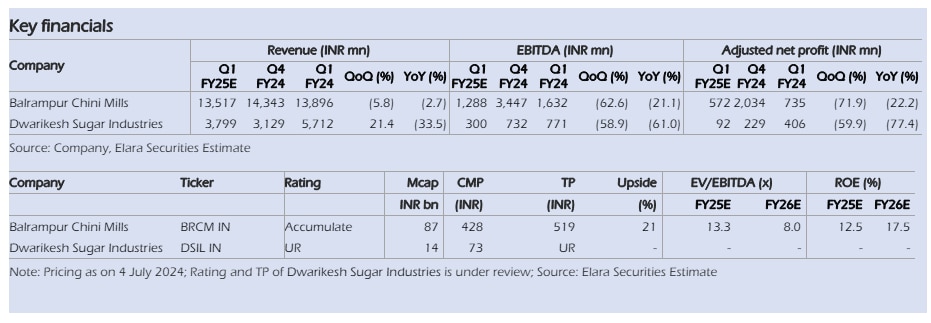



 For Balrampur Chini, Elara sees adjusted net profit declining 22.2 per cent to Rs 57.20 crore for the June quarter from Rs 73.50 crore in the same quarter last year.
The June quarter is likely to be a subdued quarter for the sugar industry due to declining sugar and ethanol volumes on account of lower year-on-year (YoY) quota allocations, Elara Securities said in its preview note. Around 5 per cent growth in sugar price and 10-13 per cent rise in blended distillery realisation would partly offset the loss of lower volume and input cost pressures, it said while preferring Balrampur Chini Mills Ltd over Dwarikesh Sugar Industries Ltd from its tracked sugar stocks.
For the quarter, the domestic sugar sales quota was up 8 per cent YoY at 7.8 million tonnes. Domestic sugar realisation stood at Rs 38.50 per kg (ex-mill), up 5 per cent YoY and largely flat sequentially. Despite the increase in domestic quota, ex-mill sugar prices have been resilient, the brokerage noted.

 Aadhaar authentication mandatory for subsidised LPG refills from October 1: Check rules
 Japan’s semiconductor push in India: Why Japanese companies are betting on materials, equipment and technology
 Tata Steel seeks fresh UK government funding as Port Talbot project faces delays
 How big is Apple Pay? US payment giant to enter India as UPI dominates digital payments
 Delhi airport gets its third runway operational; optimise aircraft movement
 CEA On India’s 7.8% Growth, Rural Incomes And Government’s Job Creation Push
 Gold Price Outlook: Why Dollar Weakness Could Keep Gold And Silver Prices Attractive Ahead
 Gold vs Silver Investment Strategy: Is This The Right Time To Buy For Long-Term Returns?
 Corporate Vs Personal Health Insurance: Which Is Better On A Budget?
 Gold Price Outlook: Why Gold Could Rise Despite Global Interest Rate Hikes | Silver Market Update

 Jindal Supreme, SS Retail, Hero Motors IPOs subscribed up to 181 times on final day; details here
 Sensex, Nifty post sixth weekly loss; TCS, Titan among top laggards, slip up to 4%
 How AI collapse could benefit Indian equity market; Jefferies' Christopher Wood explains
 Banks are no more secular growth story, prefer NBFCs: Chris Wood
 Jefferies' Christopher Wood sees gold at $10,000 'sooner or later'; likes India's small, midcaps
 Quant, Helios, Motilal Oswal: Midcap funds aren’t built the same; here’s how portfolios differ
 India’s hydrogen train may soon reach Delhi, opening a new chapter in clean rail travel
 TVS upgrades its premium bikes: New Apache and Ronin features revealed
 OpenAI’s new AI lawyer: Astra for Law could change how legal research gets done
 ₹5 lakh crore profit, not loss? SBI Research’s case for FCNR(B) scheme explained


