












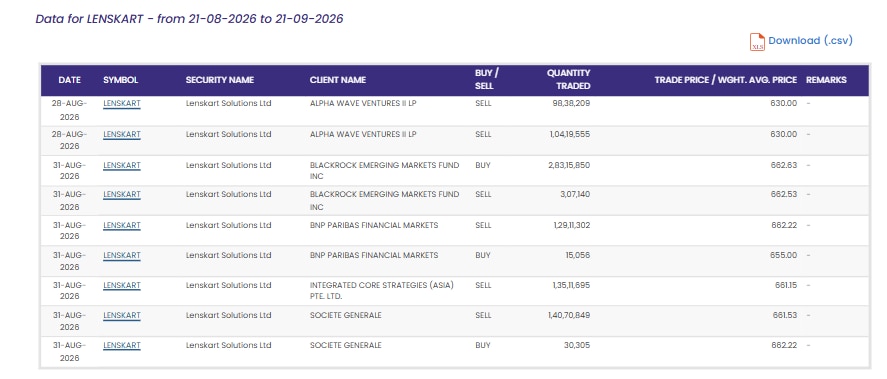



 Lenskart has been seeing block deals of late, with the stock up 79 per cent over its IPO issue price of Rs 402 apiece.
Block deal today: Lenskart Solutions Ltd is likely to see block deals on Monday, as existing shareholder Platinum Jasmine A 2028 Trust is looking to offload 3 crore shares at Rs 682.45 crore, aggregating Rs 2,047.35 crore, Bloomberg reported. The price band is at a 3.5 per cent discount to Friday's closing price, as per the term sheet.
Lenskart has been seeing block deals of late as the stock is up 79 per cent over the IPO issue price of Rs 402 apiece. The stock got listed in November 2025. The 12-month consensus target on Lenskart at Rs 693.48 implied a 1.9 per cent potential downside. Nomura has a target of Rs 888 on the stock, the highest on the Street. Ambit Capital finds it worth Rs 496, the lowest on the Street.

 Hormuz crisis exposed world's energy weak spots: Why the next shock could hurt more
 'AI ending humanity is nonsense': Ex-Infosys CEO Vishal Sikka rejects growing doom warnings
 Food delivery, quick commerce largely shielded from UPI MDR despite high digital payments
 Could AI really kill us all? Here’s what MIT researchers fear and what they don’t
 New e-commerce rules: How online discounts and search rankings will change
 Gold Price Target 2026: Expert Sees MCX Gold At ₹1.8 Lakh By Year-End Amid Strong Demand
 Health Insurance: Why Pre-Existing Diseases And Waiting Periods Matter For Buyers
 Crude Oil Above $100: How High Energy Prices And Rupee Weakness Impact Gold Prices In India
 CEA On India’s Manufacturing Rise, Atmanirbhar Bharat And Modi’s Economic Policy
 Health Insurance Buying Guide: 7 Things First-Time Buyers Must Check Before Choosing A Policy

 SpaceX weight in Nasdaq 100 to jump to 2.82% following quarterly index rebalance: Report
 Tata Motors or Ashok Leyland? Analyst reveals his preferred auto stock for near-term gains
 Maharashtra Scooters, Dixon Tech, Bharat Dynamics, Jai Corp among stocks to turn ex-dividend on Monday
 Jindal Supreme, SS Retail, Hero Motors IPOs subscribed up to 181 times on final day; details here
 Sensex, Nifty post sixth weekly loss; TCS, Titan among top laggards, slip up to 4%
 Planning a trip abroad? Nine countries revamp visa requirements for Indian travelers. Check details
 Quote of the Day by Azim Premji: 'When you are under pressure, you make the bold steps faster; you don't make the bold steps slower'
 Weather alert: IMD warns of heavy rain, thunderstorms across several states. Will Delhi get rain?
 iPhone 18 Pro launches ahead of Navratri, Diwali, but grocery and BPC could steal festive e-commerce spotlight: Report
 ‘Very big things are coming’: Trump in ‘deciding mode’ as Iran sets 7 key demands


