


 54EC bonds like NHAI and REC offer tax relief, however, experts say paying the capital gains tax and investing elsewhere might yield more.
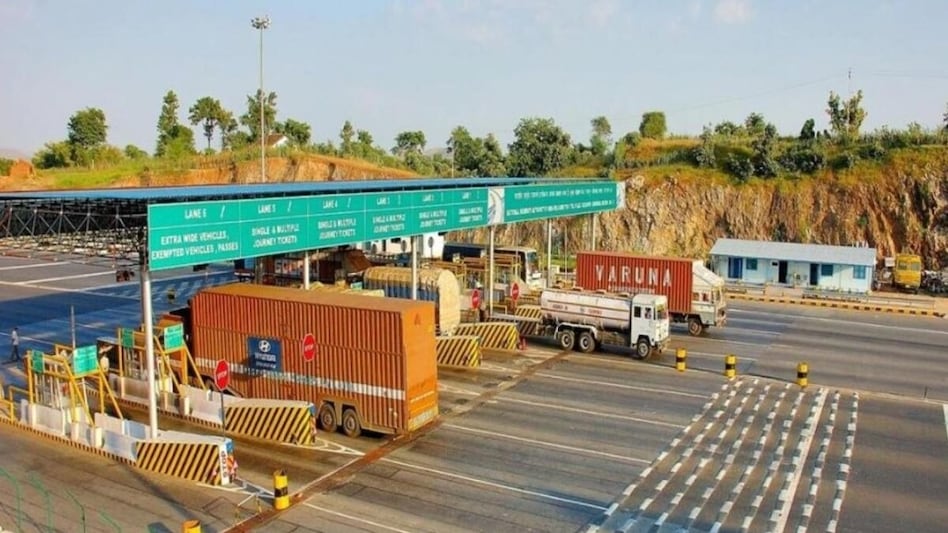
Tax relief: A taxpayer who sold his land for Rs 73 lakh to the National Highways Authority of India (NHAI) has been granted complete income tax exemption on the compensation amount, following a recent Chhattisgarh High Court decision. The court clarified that, under Section 96 of the Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013 (RFCTLARR Act), compensation awarded for compulsory land acquisition by NHAI is not subject to income tax. This verdict brings significant relief to landowners whose properties are compulsorily acquired for public projects, aligning legal protections with the intent of the 2013 Act.
The judgment follows a legal battle in which the taxpayer, Sanjay, had declared Rs 73 lakh as short-term capital gains in his income tax return, attributing Rs 53 lakh to compensation for compulsory acquisition under the National Highways Act, 1956. He paid Rs 24 lakh in tax before realising that such compensation is exempt under Section 96 of the RFCTLARR Act. Despite promptly notifying tax authorities, his exemption claim was denied, prompting appeals.

 Will RBI raise interest rates in October? Here’s what experts have to say
 Bitter Friday for Nestlé: Russia seizes assets as Moscow targets Western firms over Ukraine support
 West Asia impact: Saudi Aramco halts European crude allocations after East-West pipeline attack
 Tata Electronics partners with Japanese, Malaysian firms to boost semiconductor manufacturing in India
 From selling gold to spending ₹3.5 lakh: iPhone 18 Pro fever hits India as fans queue up on sale day
 “Unacceptable And Unprofessional”: MEA Rejects Pakistan’s Claims Over INS Kolkata Collision
 Commodity Trading For Beginners: How MCX & NCDEX Work | Trading Basics | Money Today
 US Fed Rate Hikes A Headwind For Foreign Flows? | Jibi Jacob | Jefferies
 ₹25 Billion FII Outflow: What Could Bring Foreign Investors Back? | Jefferies' Jibi Jacob
 India’s Private CapEx Picks Up: Christopher Wood On The Market Outlook

 Jindal Supreme, SS Retail, Hero Motors IPOs subscribed up to 181 times on final day; details here
 Sensex, Nifty post sixth weekly loss; TCS, Titan among top laggards, slip up to 4%
 How AI collapse could benefit Indian equity market; Jefferies' Christopher Wood explains
 Banks are no more secular growth story, prefer NBFCs: Chris Wood
 Jefferies' Christopher Wood sees gold at $10,000 'sooner or later'; likes India's small, midcaps
 Mumbai’s 100-year-old Taj hotel makes world’s top 50, jumps 8 places
 12,500 feet! Man drives e-rickshaw to Spiti Valley, documents epic Himalayan trip
 Tata Sierra Legend Series starts at ₹11.99 lakh: What Indian SUV buyers get in each new L variant in India
 Asian Games 2026 begins in Japan: India’s stars, events and how to watch live
 Who is Rajesh Rawani? Jharkhand truck driver behind 'R Rajesh Vlogs' and luxury truck













