












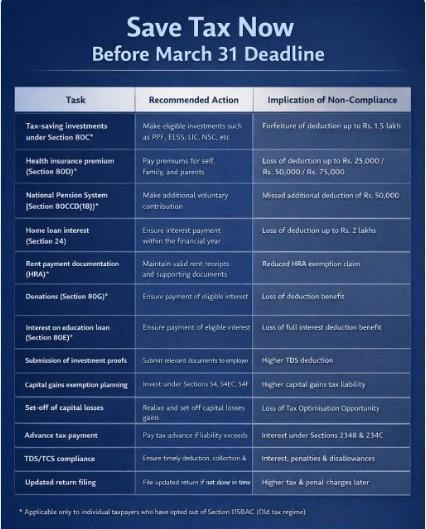



 Experts say taxpayers should also check advance tax payments, TDS/TCS compliance, and submission of investment proofs to employers.
With the financial year ending on March 31, taxpayers must complete their tax-saving investments and financial compliance tasks within the deadline to claim deductions for FY 2025-26. Experts caution that waiting until the last few days can lead to missed benefits due to bank holidays, processing delays, or documentation issues.
For deductions under sections such as 80C, 80D, 80CCD(1B), 24, and 80G, the amount must be credited to the relevant institution before March 31. Simply initiating a payment on the last day may not be enough if the funds are realised after the financial year ends.

 Tata Trusts propose merger of two Tata units with Tata Sons to avoid listing
 Essar Group's Mesabi Metallics plans $15 billion US steel mill, Trump to unveil the project
 Air India CEO-designate Tewolde lays out 5 priorities, puts safety and reliability first
 Nifty set for worst returns in 15 years, analysts weigh in
 India's industrial output hits 8% growth in August, manufacturing up 9%
 Crude Oil Next Big Commodity Bet? | Strait Of Hormuz Crisis | Commodity Outlook
 Nifty Falls: 22,500-22,300 Next? Expert Warns Against Bottom Fishing Amid Sharp Sell-Off
 Meta Muse AI & Smart Glasses, iPhone 18 Pro Max In-Depth Review & Easy iOS Data Transfer | Tech Today
 Silver Slips Below 200 DMA: Why This Crash Is A Golden Buying Opportunity | Navneet Damani
 Gold Falls $1,500 From Peak: Smart Accumulation Or Risky Bet? | Anuj Gupta

 BSE stock may test Rs 3,000 mark, says analyst; stays positive for long term
 Why HDFC Bank, TVS Motor shares are top picks amid ongoing correction
 Tata Steel shares lag peers over three months; is European business weakness priced in?Nifty set for worst returns in 15 years, analysts weigh in
 YES Bank, BOI, BoM, Union Bank, PNB, RBL Bank: Why bank stocks fell today
 Adani Group firms settle SEBI case for Rs 1.48 crore over alleged MPS violations
 FASTag annual pass crosses 1 crore mark, over 1,150 toll plazas coveredEssar Group's Mesabi Metallics plans $15 billion US steel mill, Trump to unveil the project
 Tata makes its EVs cheaper to buy upfront, under BaaS scheme
 Cleartrip checks in for a holiday-powered growth trip


