














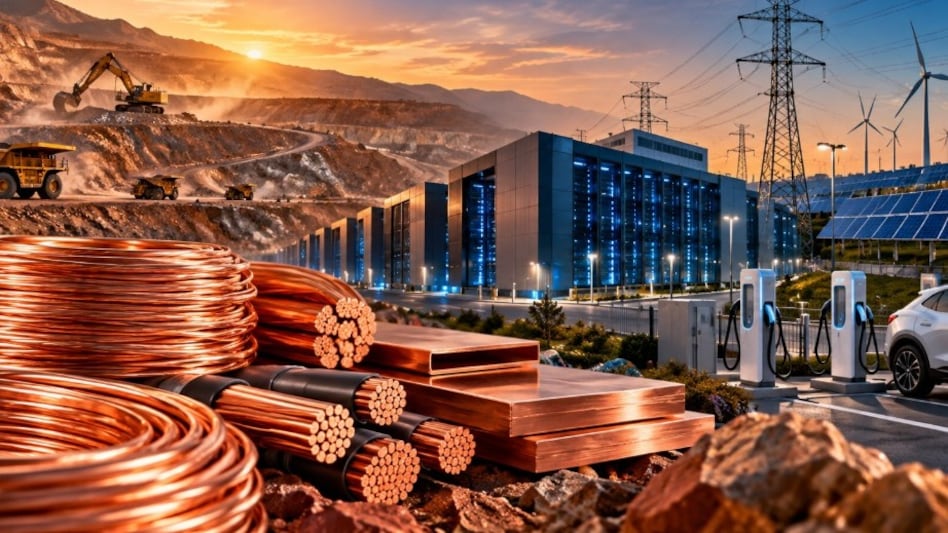
 Copper is essential for power transmission, transformers, electrical cables, renewable energy installations and EVs.
Global copper supply is facing a structural challenge as demand from artificial intelligence (AI) data centres, electricity grids, electric vehicles (EVs) and renewable energy accelerates. With mine production expected to struggle to keep pace, the market could face a significant supply deficit over the next decade, raising concerns about higher prices and constraints on industrial expansion.
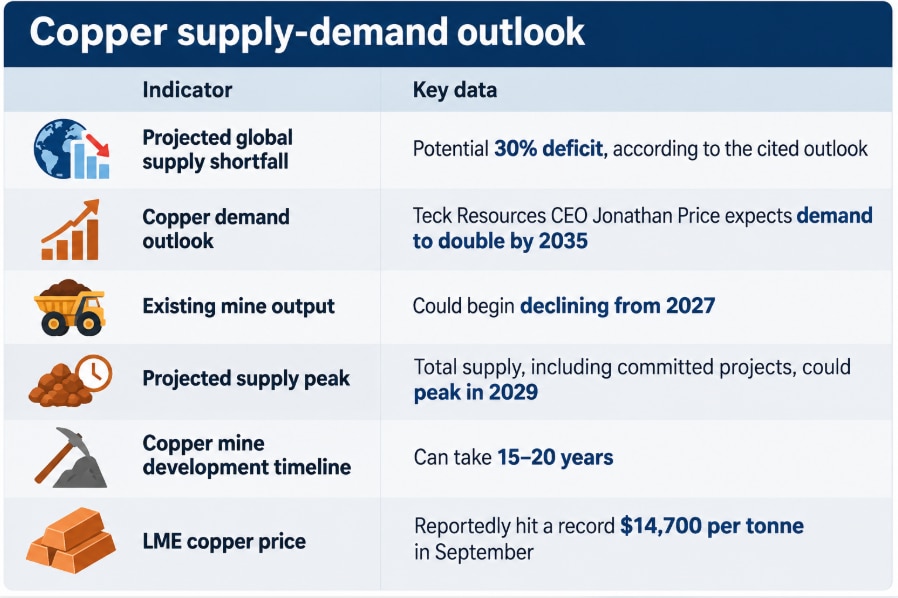
Teck Resources CEO Jonathan Price has warned that copper demand is on track to double by 2035, while supply could fall 30% short of what the market needs. The International Energy Agency (IEA) has also flagged a potential 30% supply gap, highlighting the growing mismatch between projected consumption and available mine output.

 AI revenue is surging at Indian IT firms, but how much is adding to growth?
 Festive spending in urban India to drop 6% to ₹1.97 lakh crore amid inflation: Survey
 India to overtake Japan as world’s fourth-largest economy in 2027: IMF projections
 BT Explainer: What the SC verdict on Yes Bank’s AT-1 bonds means for the lender and will it alter AT1 bonds as such?
 Stock market: India back on investors’ radar as they warm to ‘non-AI stories’, says HSBC
 Market Recovery: Gaurang Shah Picks Banking, Defence, Power And Cement Stocks For Fresh Bets
 Will IDBI Employees Lose Jobs? DIPAM Secretary Arunish Chawla Clears The Air On Pension & Benefit
 Yes Bank AT1 Bond Verdict: What It Means For Bondholders, Lenders And Shareholders
 Can Goa Become India’s Next Tech Hub? Rohan Khaunte On AI, Jobs & Investment
 What’s Hot: Stocks, Gold & Big Money Moves | Daily Markets Show | October 16 | Business Today

 CCL Products shares fall 9% on Q2 results; brokerages see up to 30% upside
 PNB Q2 earnings: Net profit rises 13%, asset quality improves
 BT Explainer: What changes for investors post revision of new Closing Auction System
 PC Jeweller shares hit 52-week high; stock jumps 75% YTD; what analysts say
 Federal Bank Q2 earnings: Net profit at record high, asset quality improves
 Radisson Blu, BigBasket, Flipkart face FSSAI action over food safety, misleading claims
 Jaishankar, Marco Rubio to hold talks in Mumbai on October 20; energy cooperation on agendaFestive spending in urban India to drop 6% to ₹1.97 lakh crore amid inflation: Survey
 EPFO extends September PF filing deadline to October 31: What employers and employees should check
 Indian enterprises are spending on AI, but workforce skills lag, say Coursera’s top executives