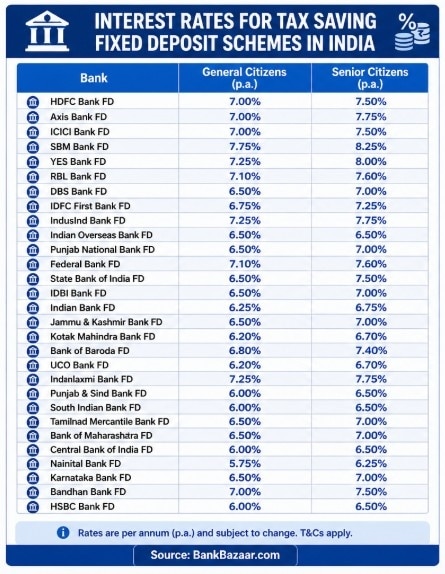



 Tax-saving fixed deposits, which come with a mandatory five-year lock-in, remain popular for investors looking to combine returns with tax benefits under Section 80C.
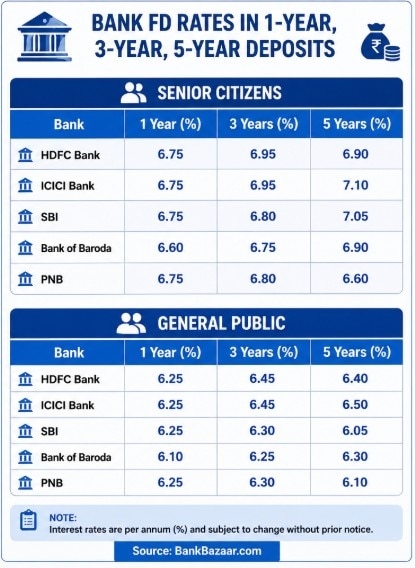
Fixed deposits (FDs) continue to remain a preferred investment option for conservative investors seeking stable and predictable returns. In May 2026, leading commercial banks are offering FD interest rates ranging from around 6.1% to 7.1% for general depositors, with senior citizens typically earning an additional 50 basis points. This makes FDs an attractive avenue for those prioritising capital protection over higher-risk instruments like equities and mutual funds.
Among public sector banks, State Bank of India (SBI) offers up to 6.05% for general investors and 7.05% for senior citizens on callable deposits up to ₹3 crore, including benefits under its ‘We-care’ scheme. Similarly, major banks such as Bank of Baroda, Punjab National Bank, HDFC Bank, and ICICI Bank are offering approximately 6.25%–6.45% for regular customers and 6.75%–6.95% for senior citizens on three-year deposits.

 'RBI letter does not mention listing': Noel Tata seeks full briefing on Tata Sons-RBI talks
 Tata Trusts asks Tata Sons to explore options other than listing, says ‘Tata Model has to be saved’
 Tata Trusts proposes ₹25,000 crore plan for SP Group, says Tata Sons listing is not an option
 Chandrasekaran had assured all necessary steps were being taken to remain private: Noel Tata
 'We cannot put the cart before...': Noel Tata's argument against N Chandrasekaran's reappointment
 How India Changed In 12 Years: PM Modi’s Journey From Economic Reforms To Viksit Bharat
 Modi @76: From Twitter To Instagram, How His Digital Outreach Has Evolved
 Stock Picks To Watch: Shibani Kurian Reveals Kotak AMC’s Market Bets
 Gold ETF vs Physical Gold: Know the Tax Rules, Charges and Key Differences
 PPF vs NPS: Tax Benefits, Returns and Lock-in Period Explained for Retirement Planning

 Hero Motors IPO subscribed 3.37 times on Day 2; retail portion subscribed over 5 times
 NSE IPO: India's largest exchange gets 43% subscription on Day 1; NIIs, retail see strong demand
 Rentomojo shares settle maiden trade nearly 32% above IPO price; what should investors do now?
 Sensex slips, Nifty settles higher; Tata stocks gain after N Chandrasekaran reappointment
 Cochin Shipyard, KRBL, RITES, Ramky Infrastructure among stocks to turn ex-dividend on September 18
 Maharashtra FDA action: Nair Hospital canteen, Olympia Coffee House licences suspendedChandrasekaran had assured all necessary steps were being taken to remain private: Noel Tata
 TVS Motor to increase monthly EV capacity to over 50,000 units as sales boom
 'Foreign investors want only returns': Noel Tata explains why he opposes listing Tata SonsTata Trusts proposes ₹25,000 crore plan for SP Group, says Tata Sons listing is not an option